When Should an Indian Company Hire an Internal Audit Support Team? Signs, Options & S.138 Rules
If your finance team keeps missing audit deadlines, or the same control gaps show up review after review, you likely need an internal audit support team. This is the point where most growing companies in India start looking at internal audit outsourcing or a co-sourced internal audit model instead of stretching an already thin in-house team further.
Under Section 138 of the Companies Act, 2013 and Rule 13 of the Companies (Accounts) Rules, 2014, every listed company, and unlisted public and private companies above prescribed turnover, borrowing, paid-up capital or deposit limits, must appoint an internal auditor. The law sets the floor. For CFOs and Audit Committee members, the real question is when workload and risk demand more than that.
This article covers the signs to watch for, the internal audit staffing options available, and how to decide between building in-house and bringing in outside help
What Does an Internal Audit Support Team Do?
An internal audit support team adds capacity, skills, or independence to your audit function without replacing it.
Depending on what your company needs, this support can look like:
- A specialist brought in for one complex area, such as IT controls or third-party risk
- Extra hands during a busy quarter when your team cannot cover the full audit plan
- A fully outsourced internal audit support function for a company with no in-house auditors yet
- Ongoing co-sourced internal audit arrangements where your team and an external firm split the work
The common thread across all four: the support team works within your existing structure, reporting lines, and audit charter, not outside your governance framework.
Which Indian Companies Must Appoint an Internal Auditor Under Section 138?
Section 138 and Rule 13 make an internal auditor mandatory for the companies below. The internal auditor may be a Chartered Accountant, a Cost Accountant or another professional the Board decides, and may or may not be an employee.
Company type | Mandatory when |
Listed company | Always |
Unlisted public company | Paid-up capital ≥ ₹50 cr, turnover ≥ ₹200 cr, borrowings > ₹100 cr, or deposits ≥ ₹25 cr in the preceding financial year |
Private company | Turnover ≥ ₹200 cr or borrowings > ₹100 cr in the preceding financial year |
The Audit Committee, or the Board where there is no committee, decides the scope and frequency of the audit.
What Are the Early Signs You Need an Internal Audit Support Team?
Most companies do not wake up one day and decide to hire internal audit support. The need builds up quietly over a few quarters.
Watch for these patterns:
- Audits run behind schedule. Your risk-based audit plan keeps slipping because the team gets pulled into other finance work.
- The same findings repeat. Control testing flags the same issues because nobody has time to follow up on remediation.
- One person carries too much. A single internal auditor plans, tests, reports, and follows up across every business unit.
- Specialist areas go untested. Cybersecurity, IT controls, or vendor risk sit outside your team’s skill set, so they simply don’t get audited.
- The audit committee asks harder questions. Growth, a fundraise, or a new regulator has raised expectations your current team can’t meet.
Two or three of these together, over consecutive quarters, is usually a strong signal.
An illustrative example (not a real client):
Consider a private company whose turnover and borrowings are both below the Rule 13 limits. It has one internal auditor covering five business units. Its lender asks for IT-controls testing ahead of a credit-limit renewal. The in-house auditor has no IT audit background, so the audit plan slips by two quarters while the team tries to build the skills. A co-sourced specialist engaged for that one area may help close the gap without adding permanent headcount, while the in-house auditor keeps ownership of planning and reporting.
How Do You Know If Your Audit Coverage Has Gaps?
Audit coverage gaps show up on paper before they show up in daily operations. A simple way to check is to compare your annual risk-based audit plan against what actually got completed.
Question to ask | What it tells you |
Did every high-risk area get audited this year? | Reveals coverage gaps in critical processes |
How many audits were postponed or shortened? | Signals a workload or staffing gap |
Are specialist risks (IT, fraud, ESG) part of the plan? | Shows where specialist skills are missing |
How long to close a finding after it’s raised? | Points to a bandwidth problem, not just skill |
If your answers show recurring gaps rather than one bad quarter, that’s structural. A single busy month is normal. A pattern across two or three cycles usually means the business has outgrown the team’s capacity.
In-House Team vs Internal Audit Outsourcing: What's the Real Difference?
This choice depends on your company’s size, the budget, and how often you need the coverage.
Factor | Building an in-house team | Internal audit outsourcing | |
Speed to get started | Slower; hiring and onboarding take months |
| |
Cost structure | Fixed salaries, benefits, and training year-round | Pay for the scope and hours actually used | |
Specialist skills | Limited to what your hires already know | Access to auditors with varied sector experience | |
Institutional knowledge | Builds up over time within the company | Needs a clear handover process each engagement | |
Best suited for | Larger companies with steady, year-round audit needs | Growing or mid-sized companies with variable audit needs |
Neither option is automatically better. A company with a stable, predictable calendar often benefits from an in-house team over time. A company still scaling, or one needing specialist coverage occasionally, tends to get more value from outsourced support.
What Is Co-Sourced Internal Audit and When Does It Make Sense?
Co-sourced internal audit sits between the two extremes above. Your in-house team keeps ownership of planning and reporting while an external partner fills specific gaps. This model tends to work well when:
- You already have one or two internal auditors, but not enough hands for the full plan
- You need a specific skill, such as data analytics or IT audit, for a handful of engagements a year
- You want to keep strategic control of the audit function while adding flexible capacity around it
- Your audit committee wants continuity, with an internal owner who understands the business
Co-sourcing is not a replacement for governance. The findings, risk assessments, and final reports still go through your internal audit head or CAE. The external team supplements the work rather than taking over accountability for it.
Does Bringing in Internal Audit Support Affect Independence?
This is a fair question, and a common one from audit committees.
Independence in internal audit is about who the function reports to and how its scope is decided, not who performs the fieldwork. A well-structured support arrangement, whether outsourced or co-sourced, still reports findings to the audit committee or board rather than the department being reviewed. The support team follows the same audit charter and risk-based audit plan that governs your internal function.
What actually threatens independence is different: an auditor reviewing their own work, or a support team taking direction from the managers whose processes they’re testing. As long as reporting lines stay clean, adding external capacity doesn’t weaken the function. A specialist from outside can strengthen independence, since they carry no prior relationship with the teams under review.
Can Your Statutory Auditor Also Provide Internal Audit Support?
No. Section 144 of the Companies Act, 2013 bars a company’s statutory auditor from providing internal audit services to it, or to its holding or subsidiary company. The bar applies “indirectly” too, so it reaches the auditor’s partners, parent, subsidiary and associate entities, and entities carrying its brand.
Before appointing a support provider, confirm it has no statutory audit relationship with your company or group, and record that check in the engagement letter. For listed companies, the Audit Committee also reviews the adequacy of the internal audit function under Regulation 18(3) and Part C of Schedule II of the SEBI (LODR) Regulations, 2015.
How Does Internal Audit Staffing Scale With Company Growth?
Internal audit resources rarely scale in a straight line. Growth arrives in bursts: a fundraise, a new product, a new state, and each burst adds scope faster than most teams can hire for.
A few common growth triggers and what they typically mean for coverage:
- A funding round. Investors and lenders often expect stronger controls and more frequent reporting.
- Entering a regulated sector. New RBI or SEBI requirements can add audit scope overnight.
- Geographic expansion. New locations mean new risks your current team hasn’t visited yet.
- Headcount growth. More employees and transactions widen the surface area for error or fraud.
Building permanent headcount for every growth spike is expensive and slow. Scalable audit staffing lets a company match capacity to its actual risk profile, rather than staying a step behind it.
The IIA’s 2024 North American Pulse of Internal Audit found that 60% of internal audit functions use outsourcing or co-sourcing to cover assurance gaps, often in technology areas such as cybersecurity and IT. Only 32% of the smallest functions do
What Are the Benefits of an Internal Audit Support Team?
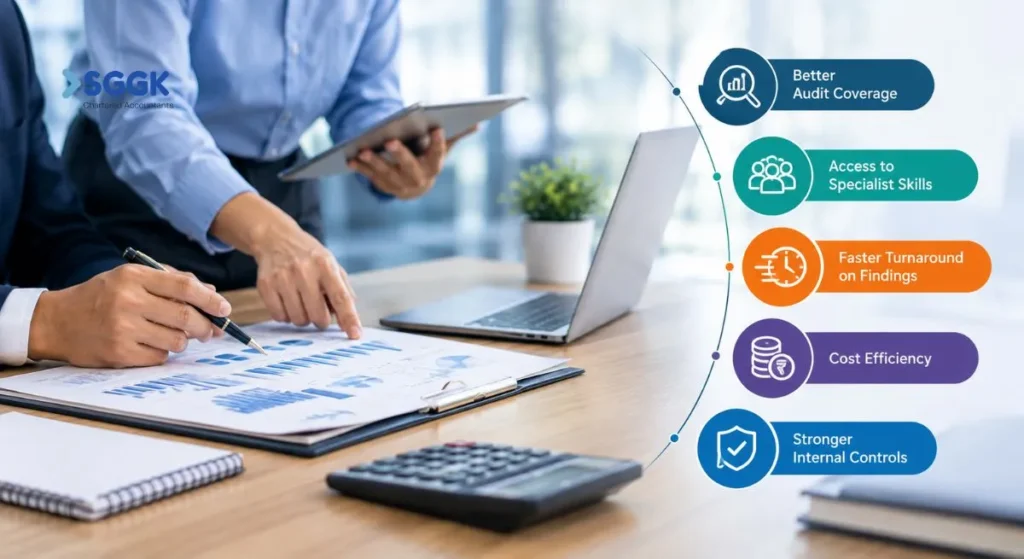
Internal audit benefits go beyond having more people available. Companies that use support well tend to see:
- Better audit coverage, with high-risk areas tested on schedule instead of deferred
- Access to specialist skills in IT controls, fraud risk, or ESG reporting without a full-time hire
- Faster turnaround on findings, since work isn’t queued behind other finance priorities
- Cost efficiency, paying for capacity when it’s needed instead of carrying it year-round
- A second, independent set of eyes on processes the internal team may have grown too close to
What Are The Common Mistakes Companies Make When Hiring Internal Audit Support Team ?
Internal audit support is often sought only after an external trigger, such as a lender or investor question about controls. These patterns are common:
- The trigger is external, not internal. A lender or investor asks a pointed question about controls, and only then does the company look for support, reacting under pressure instead of planning on its own timeline.
- Support is a one-off rescue, not a staffing model. A company clears a backlog once and never builds a repeatable way to add capacity next time volume spikes. Companies that handle growth well treat support as a resource they can dial up or down.
- Scope is agreed verbally and never written down. This is the mistake we push back on most. Without a scope document, the in-house team and the outside firm both assume the other is covering an area, and the gap surfaces months later.
- Provider selection is based on price alone. Companies evaluating providers may weigh scope, sector familiarity, team composition, and reporting quality alongside fees. A written scope and a defined handover process help the engagement fit the company’s needs. .
None of these mistakes is unusual. What matters is catching the pattern before the audit committee starts asking questions you don’t have good answers to.
When Should You Actually Make the Call?
There is no single trigger that applies to every company. A useful way to frame it: can your current team deliver the full risk-based audit plan this year, with the specialist skills it requires, on the timeline your audit committee expects?
A clear yes usually means you’re fine for now. A no, especially if it has repeated for a quarter or two, is a reasonable point to start evaluating internal audit outsourcing or a co-sourced model. If the answer stays no across consecutive quarters, it may be time to evaluate outsourced or co-sourced options before the next audit cycle.
Consulting an internal audit support services professional in Bangalore can help you assess how these factors apply to your specific situation and regulatory obligations.
Need to Strengthen Your Internal Audit Function?
Frequently Asked Questions About Internal Audit Support Team
Is internal audit outsourcing allowed under Indian law?
Yes. Section 138 of the Companies Act, 2013 requires certain companies to appoint an internal auditor, but the role does not need to be an employee.
Can a small or medium-sized firm adopt a co-sourced internal audit approach?
Yes. Co-sourcing works well for firms that already have some internal audit capability but need to augment specific skills such as data analytics or IT audit for particular engagements.
Does outsourcing of internal audit support diminish the accountability of management?
No. Management stays accountable for internal controls even when an external team carries out the audit work.
What Is Audit Readiness? Meaning, Process & Services
October 8, 2026[…] groups and mid-sized to large businesses across India. If you are weighing options, our guide on when an Indian company should hire an internal audit support team may […]